Commission may not drop to zero, but it can be reduced. The TL offer at the POS, your card's statement type and currency determine the cost; some rules are bank-specific.
The answer to how to avoid commission on overseas spending is conditional: avoiding it completely is not guaranteed, but it can be reduced. Reject the TL offer at the POS and pay in the local currency, and find out your card's statement type. Since the rate varies from card to card, check your bank's current fee and commission information before you travel.
In short
- Rejecting the TL offer at the POS and paying in the country's local currency helps reduce the extra markup caused by DCC.
- The statement rules here are based on Garanti BBVA sources; ask your own bank about its practice beforehand.
- Foreign currency statement debt is charged in that currency at this bank and converted to TL if not paid in full.
- Commission varies from card to card; it may not disappear entirely, so read the current fee information before departure.
The core rule: two decisions affect the cost
When paying by card abroad, cost arises in two places: at the POS screen at the point of sale, and in your card's payment type setting. Both are largely your decision, but the rules for the second decision can vary from bank to bank.
First, if the POS screen offers TL, reject this offer and pay in the country's local currency. Second is your card's payment type. The statement rules in this article are based on Garanti BBVA/Bonus and Miles&Smiles sources; do not assume they are the same at other banks.
The practical sequence is as follows:
- Reject the TL offer at the POS, pay in local currency.
- Ask your bank about your card's payment type and the foreign currency statement option.
- If a foreign currency statement is offered, find out how and in which currency the debt will be paid.
Since the commission rate varies from card to card, we don't give a rate on this page. Read your bank's current fee and commission table before traveling. These steps help reduce the cost, but do not promise that commission will disappear entirely.
Why the TL offer (DCC) at the POS is costly
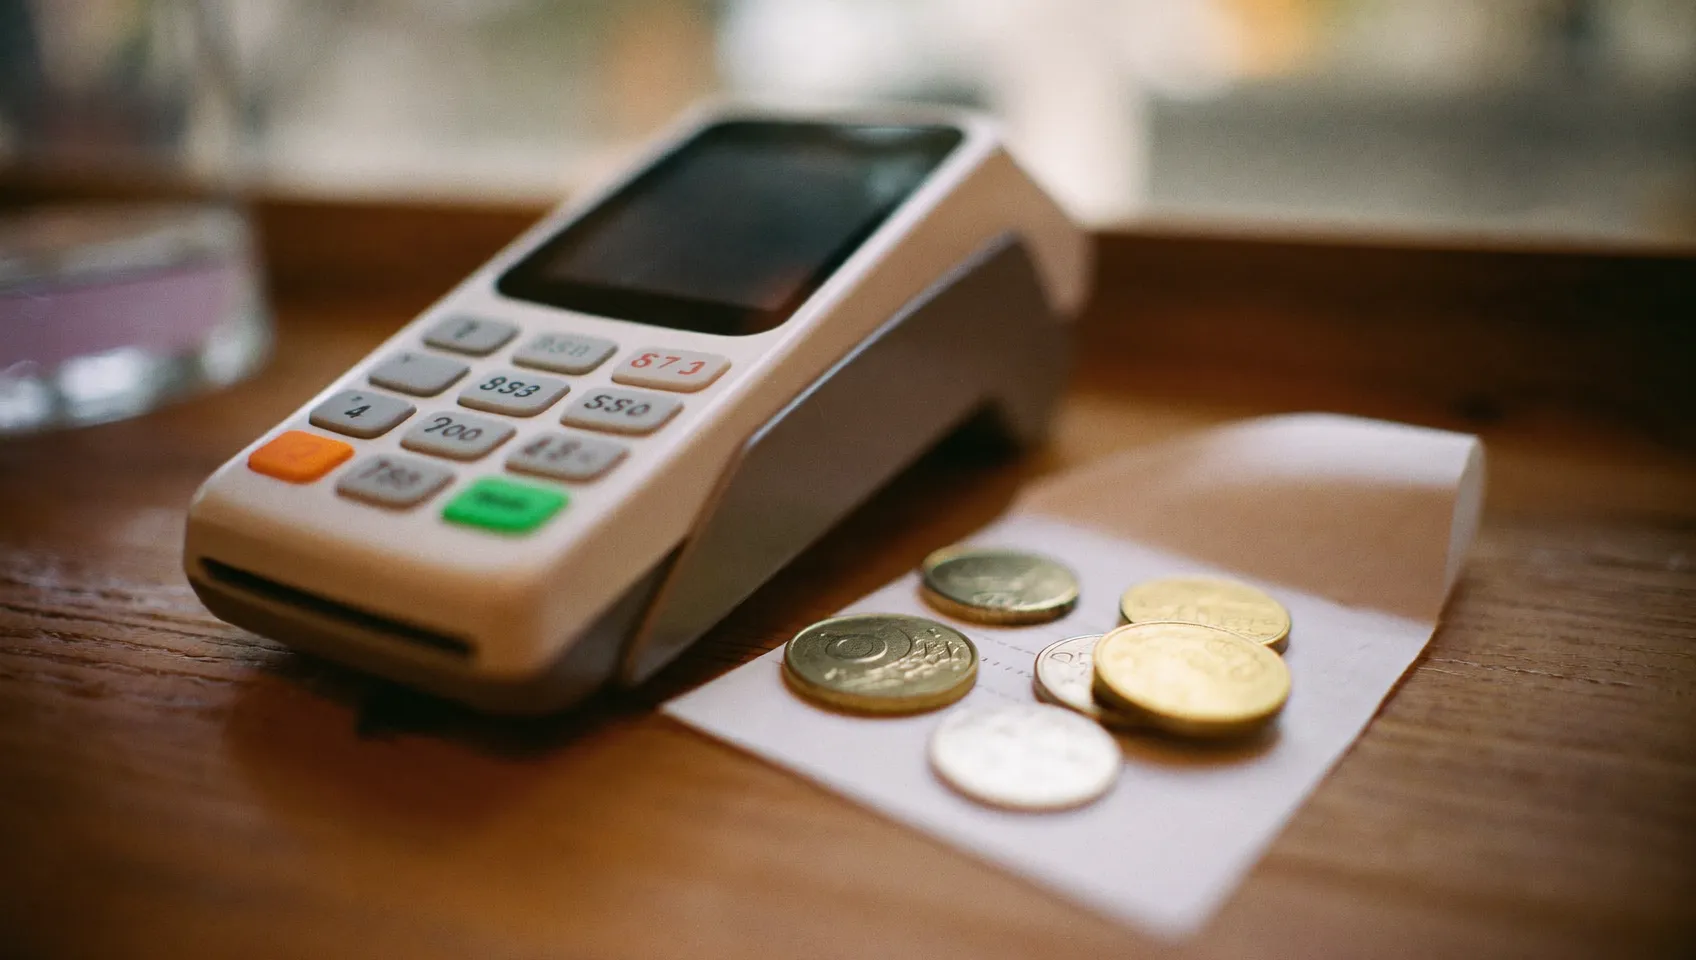
DCC means Dynamic Currency Conversion. The POS device abroad shows the amount in TL and asks if you want to pay in TL. Seeing the price in a familiar currency feels comfortable; however, according to Yapı Kredi's DCC POS page, the converted amount is calculated by adding the DCC commission to the original amount. According to the same page, the offer shows the original amount, exchange rate and commission rate.
According to İş Bankası's DCC POS page, the amount that will appear on your statement is found by adding a markup to the foreign exchange buying rate at the time of the transaction. When you approve this amount, the transaction is completed. In other words, pressing the approve button means accepting that rate and the added markup.
Information websites write that DCC involves a high and hidden exchange rate margin. This is not an official source; still, it is a warning in the same direction as the commission and markup statements on the bank pages.
What to do at checkout
- If you see a TL amount on the screen, look for the reject option.
- Select the country's local currency.
- If necessary, tell the cashier to charge the card in the local currency.
- Read the amount and currency on the screen before approving.
- Check that the currency is written correctly on the receipt.
Statement type: TL or foreign currency
Your card's payment type determines how the spending will be recorded on your statement. The rules below are found in Garanti BBVA/Bonus and Miles&Smiles Garanti BBVA sources. At another bank, the option name, scope and conditions may differ; check your bank's current rule.
TL payment type
According to Garanti BBVA/Bonus, if the TL payment type is selected, overseas spending is converted to TL at the bank's foreign exchange selling rate at the moment it reaches the bank's record from the card scheme's clearing. Any Foreign Exchange Transaction Tax that may arise is paid by the cardholder. Since the rate is applied at the time of recording, not at the time of spending, you cannot know the exact amount on the day of the transaction.
Foreign currency payment type
According to Miles&Smiles Garanti BBVA, if the foreign currency payment type is selected, EURO and USD spending, excluding cash or cash-equivalent transactions, is charged to the statement in the same currency and the same amount. Therefore, the bank's TL conversion is not applied.
The condition for this is how the debt is paid: the entire foreign currency statement debt must be paid in the relevant foreign currency by the due date. If paid partially, late, or not at all, the remaining debt is converted to TL and the Foreign Exchange Transaction Tax is passed on to the cardholder. If you won't be able to pay off the debt in full, this option may not provide an advantage.
Differences: euro, dollar and other currencies
According to the Miles&Smiles Garanti BBVA source, the foreign currency statement does not work the same way for every currency. EURO and USD spending is charged to the statement in the same currency. Spending in currencies other than these two, even if the FX statement is selected, is first converted to USD at the rate determined by card scheme organizations. It is then charged to the statement in USD along with the fees and commissions added by these organizations.
As a result, this option may provide a clearer benefit in a country where euro or dollar is used. For example, if you are planning your Germany route, most of your spending will be in euros. In countries using a different currency, a two-step conversion applies. In this case too, rejecting the TL offer at the POS means not accepting the amount with the added DCC commission or markup.
Evaluate cash withdrawal separately
The rule above does not cover cash or cash-equivalent transactions. If you will withdraw cash from an ATM, ask your bank separately about cash advance and overseas ATM fees. Since fees vary from card to card, we don't give figures here.
Common mistakes
Extra costs can arise when rushing at checkout. The most common mistakes are:
- Approving the TL offer out of convenience. The TL amount on the screen is the amount with DCC commission or markup added.
- Selecting a foreign currency statement and trying to pay the debt in TL. According to the Garanti BBVA source, the debt must be paid in the relevant foreign currency.
- Partially paying the statement debt. The remaining debt is converted to TL and the Foreign Exchange Transaction Tax is passed on to the cardholder.
- Expecting the same advantage in every currency. Spending other than EURO and USD is first converted to USD.
- Applying the same rule to cash withdrawal. Cash or cash-equivalent transactions are excluded from this rule.
- Applying one bank's rule to every bank. The statement details in this article are based on a specific bank's sources.
- Assuming the rate is the same for everyone. The overseas commission rate varies from card to card.
Another mistake is relying on a single source. Comparison and information websites provide guidance but are not official. The final word belongs to your bank's own fee schedule and card agreement.
Step by step: before departure and at the time of payment
The sequence below helps reduce commission; the exact outcome depends on your bank's rules.
- Call your bank or check the app. Find out the overseas commission rate, cash withdrawal fee, and payment type option.
- Decide on the statement type. If your bank offers a foreign currency statement and you will pay off the debt in full and on time in the relevant currency, consider this option.
- Prepare your payment source. The foreign currency debt will be paid in the relevant currency by the due date.
- Watch the screen at checkout. If a TL offer appears, reject it and select the local currency.
- Keep the receipt. Compare it with the statement when you return; if the amount or currency doesn't match, contact your bank.
If you are planning a package tour, paying for major items in advance and covering only additional spending by card on-site reduces the amount of spending made by card. You can look at overseas tours for options. If you are planning for a holiday period, you can check 4-day overseas route suggestions for October 29 and divide your budget into spending categories.
Pre-departure checklist
Check off the following items before departure:
- The bank's current overseas fee and commission information has been read.
- The card's payment type has been learned; if a foreign currency statement is offered, the conditions have been asked and a selection made if necessary.
- If a foreign currency statement is selected, the source for paying off the debt in full in the relevant currency is clear.
- It is known whether the destination country's currency is EURO, USD, or something else.
- The decision to reject the TL offer at the POS has been made.
- The cash withdrawal fee and limit have been learned.
- A backup payment method has been set aside.
- Spending notifications are turned on in the banking app.
Also finish your document and flight preparations in advance for travel day; read the online check-in steps to save time at the airport. If you have a visa plan, check the Schengen trusted traveler formula article. Planning your spending together with your visa and flight plan reduces surprises.
Frequently asked questions
Why can paying in TL abroad be more expensive?
The TL offer at the POS is calculated with DCC, and according to bank pages, DCC commission or markup is added to the original amount. When you approve, this amount becomes final. For this reason, paying in local currency is generally a more accurate choice.
If I choose a foreign currency statement, does the commission disappear entirely?
No, it may not disappear entirely. According to the Miles&Smiles Garanti BBVA source, the bank's TL conversion is not applied to EURO and USD spending. Other currencies are first converted to USD, and fees and commissions from card scheme organizations are added; cash transactions are also excluded from the rule.
What happens if I pay a foreign currency statement debt in TL?
According to the Garanti BBVA source, the entire debt must be paid in the relevant foreign currency by the due date. If you pay partially or late, or not at all, the remaining debt is converted to TL and the Foreign Exchange Transaction Tax is passed on to you. Also check your bank's rule.
Is the overseas commission rate the same for all cards?
No. The overseas commission rate varies from card to card. Check your bank's current fee and commission information before traveling.
Should I choose TL or local currency at the POS?
If possible, select the local currency and reject the TL offer. The TL amount on the screen may have been calculated by adding DCC commission to the original amount. Check the amount and currency before approving.
Who bears the Foreign Exchange Transaction Tax?
According to the Garanti BBVA/Bonus source, if the payment type is TL, any Foreign Exchange Transaction Tax that may arise is paid by the cardholder. If the foreign currency statement debt is not paid in full and on time, the Foreign Exchange Transaction Tax is also passed on to the cardholder when the remaining debt is converted to TL.
Sources
- Using Your Card Abroad — bonus.com.tr
- Miles&Smiles Garanti BBVA - Using Your Credit Card Abroad — milesandsmilesgarantibbva.com
- DCC POS > Our Payment Solutions > Yapı Kredi POS — yapikredipos.com.tr
- Dynamic Currency Conversion - DCC POS — isbank.com.tr
- What You Need to Know About Using Credit Cards Abroad — hangikredi.com
- Overseas Spending Credit Card Commission Rates — hesapkurdu.com
My Travel Team
Travel Editor
The My Travel team prepares up-to-date travel, visa and tourism information and guides.